0207 608 5500


Search ideas, news and case studies
Blog Categories
Our Practical Guide to Starting Your Home Florist Business
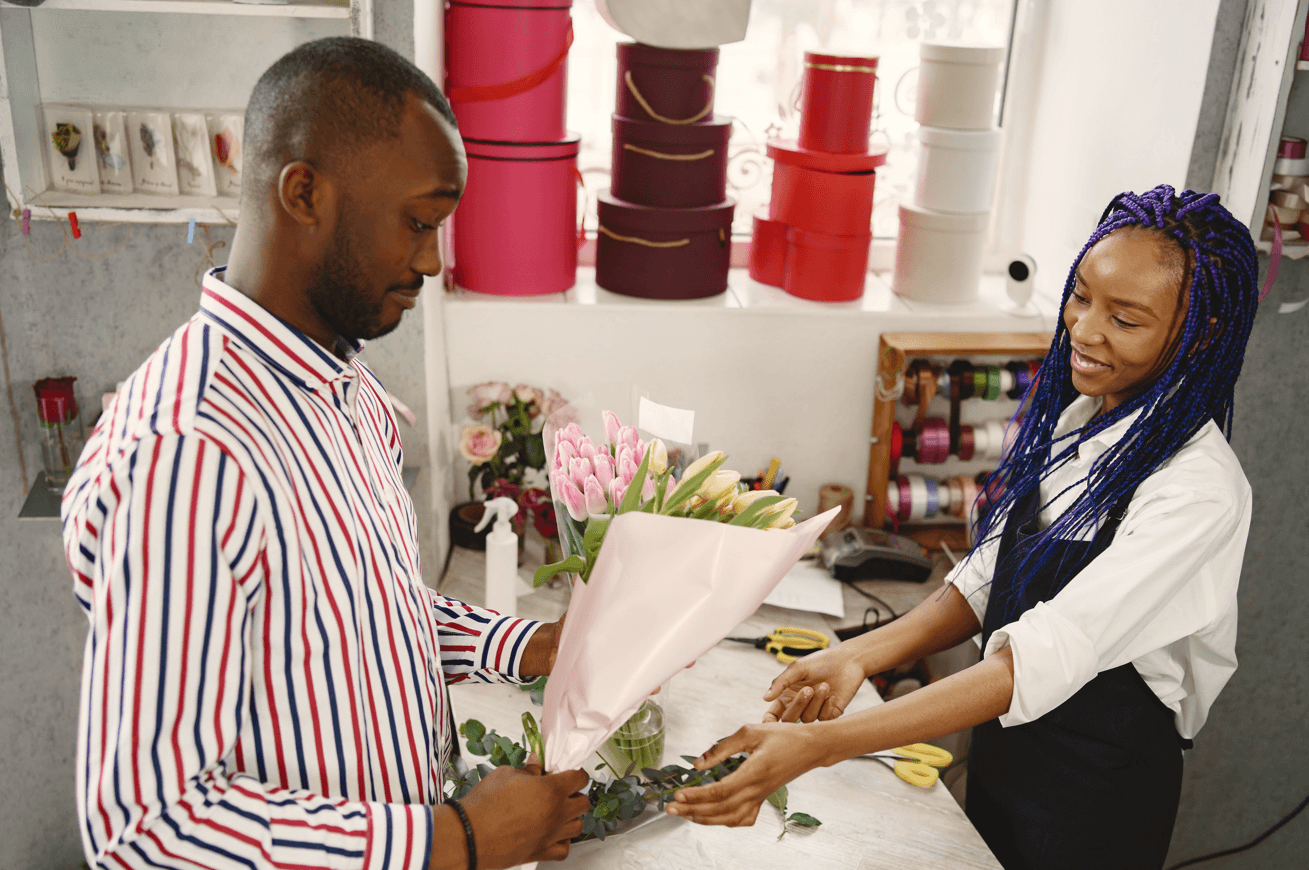
Few businesses are more rewarding for your creativity than arranging stunning bouquets, and floristry is genuinely well suited to running from home. Beyond picking the right flowers and finding your creative signature, though, there's a real set of business fundamentals worth getting right before you launch.
Key Takeaways
- Decide whether to operate as a sole trader for simplicity, or form a limited company to protect your personal assets.
- Health and safety obligations apply from day one, though a formal written policy only becomes a legal requirement once you employ five or more people.
- Public and product liability insurance protect your business from accidental claims, and standard motor insurance usually excludes business deliveries.
- Fresh flowers are classified as perishable goods, exempting them from the standard 14-day online cancellation right, though your other consumer rights obligations still apply.
- Working from home keeps start-up costs genuinely low, avoiding the overheads of a physical retail space.
Setting Up Your Company and Understanding the Law
Before selling a single bouquet, you'll need to decide whether to trade as a sole trader or set up as a limited company. Sole trader status is faster and simpler; a limited company keeps your personal assets separate from the business. Either way, a dedicated business bank account makes tracking expenditure and cash flow considerably easier.
Health and safety obligations apply regardless of your size. You're legally required to assess and manage risks for yourself, your customers, and any staff, covering things like allergies, sharp tools, and safe handling of chemicals or fertilisers, and to know how to safely store and dispose of anything hazardous. A formal written health and safety policy only becomes a legal requirement once you employ five or more people, but managing the risks themselves applies from day one.
If you sell to the public, public liability insurance protects you against customer accidents, and product liability insurance is worth having too, in case a customer has an adverse reaction to a plant. Legal expenses and business interruption cover are also worth considering, the latter protecting your income if an injury or disruption stops you working. If you use your own vehicle for deliveries, check your motor insurance actually covers business use, since standard domestic policies usually exclude it.
Selling online brings its own rules under the Consumer Rights Act and distance-selling regulations. Flowers must be delivered on the agreed date, or within 30 days if none was specified, and must match their description and images, so it's worth keeping your product photography accurate rather than just beautiful. One genuine exception worth knowing: fresh flowers are classified as perishable goods, which exempts them from the standard 14-day cancellation right most online purchases carry, though it's worth stating this clearly in your own terms and conditions rather than assuming customers will know.
If you're weighing up registering as a limited company alongside sorting your insurance, our formation packages can take the admin off your plate so you can focus on the flowers themselves.
Managing Your Start-Up Costs
Running a florist business takes more than sourcing beautiful, fresh stock daily, you'll also need tools, packaging, and a way to actually get orders to customers. Working from home or selling primarily online keeps your initial costs considerably lower, since you're avoiding retail rent, energy bills, and the other overheads that come with a physical premises, genuinely unnecessary unless you're planning to hire staff and need the space.
Making Your Business Stand Out
The florist market, both high street and online, is genuinely crowded, so finding something distinctive matters. Using native or seasonal varieties, or building your business around sustainable and eco-friendly practices, are both good starting points.
Get clear on your actual message and who you're trying to reach, then let that shape your approach. Follow trends where they genuinely fit, but stay recognisably yourself rather than chasing every one.
Getting Social
Customers need to find your work before they can fall in love with it, which is exactly where a strong social and online presence earns its keep. A website that's easy to use, discoverable on search engines, and genuinely well presented is the foundation, Instagram, Pinterest, Facebook, and TikTok are the obvious channels beyond that, given how visual floristry naturally is.
Decent photography matters more than expensive equipment, most phones handle this well now, but a poorly lit or badly angled photo can cost you a sale regardless of how good the arrangement actually is. Location hashtags and geotagging help local customers find you, and posting when your audience is actually online, a commute, a Sunday evening, matters more than people tend to assume. Genuine engagement, replying to comments, using stories or Q&A features, tends to pay off more than posting alone.
Reviews matter too, particularly early on while you're building a customer base. Encourage happy customers to leave one on Google or Facebook, and when a negative one comes in, reply calmly and take any fair criticism on board rather than getting defensive. None of this replaces the fundamentals, though: excellent service and word of mouth remain the real engine behind a florist business.
FAQs
Do I need a licence to start a florist business from home?
Not typically. You'll need to register your business with HMRC as a sole trader, or incorporate through Companies House if you're forming a limited company. Selling from a public pop-up stall may require a separate street trading licence from your local council.
Should I register as a sole trader or a limited company?
It depends on your growth plans and appetite for risk. Sole trader status is the simplest and fastest route, but leaves you personally liable for business debts. A limited company protects your personal assets and can be more tax-efficient as turnover grows.
What insurance does a home-based florist need?
Public liability insurance at minimum, plus product liability insurance in case a customer reacts badly to a plant. If you use your own vehicle for deliveries, check your motor insurance actually covers business use.
How do I comply with health and safety regulations as a florist?
Carry out risk assessments covering sharp tools, heavy lifting, and plant-related allergies or irritation. A written health and safety policy is only a legal requirement once you employ five or more people, but managing the risks applies regardless of size.
What are the delivery rules for selling flowers online?
Flowers must match their description and be delivered by the agreed date, or within 30 days if none was specified. Fresh flowers are exempt from the standard 14-day cancellation right, since they're classified as perishable goods, worth stating clearly in your own terms.
How can I keep my start-up costs low?
Working from home avoids retail rent and utility overheads entirely. Buying tools and packaging in bulk, relying on free social media marketing, and starting with a made-to-order model to cut waste all help too.
How do I find my target audience for a floral business?
Decide on a focus, weddings, everyday bouquets, or corporate events, then use location-based hashtags and geotagging to reach local customers. A strong photo portfolio and genuine reviews do most of the trust-building from there.
This article is for general information only and does not constitute legal, tax, or financial advice. Consumer protection and health and safety requirements can change, so it's worth checking current guidance on GOV.UK.